Most debt payoff guides present the Avalanche and Snowball methods as simple alternatives without explaining the actual trade-off between them, or clarifying which of the five strategies here should be your starting point based on your specific situation. After reviewing the debt payoff journeys of people who successfully eliminated high-interest debt — some taking years, others accelerating to under 18 months — one pattern stood out consistently: the people who finished weren’t always the ones with the highest income. They were the ones who matched their strategy to their behavioral tendencies, not just the math. This guide on how to pay off debt fast fills those gaps with the reasoning, not just the steps.
Why Debt Payoff Often Beats Investing — The Math Made Explicit
Credit card interest rates commonly range from 15% to 30% annually. This isn’t just “expensive” in a general sense — it’s a guaranteed, certain cost, whereas investment returns are never guaranteed. Paying off a 20% interest debt is mathematically equivalent to earning a guaranteed 20% return, something no legitimate investment can promise.
This is precisely why financial advisors typically recommend prioritizing high-interest debt payoff before aggressive investing: you’re comparing a certain “return” (interest saved) against an uncertain one (market returns), and the certain option wins on pure expected value in nearly every realistic scenario.
For context on typical market returns to compare against, see Investopedia’s guide to average investment returns.
Strategy 1: The Debt Avalanche Method — Optimal Math, Requires Patience
Ordering debts from highest to lowest interest rate and attacking the highest-rate debt first minimizes the total interest paid over the life of your debt payoff — this is mathematically the fastest and cheapest path to becoming debt-free, full stop.
The catch this method doesn’t advertise: if your highest-interest debt also happens to be your largest balance, you might work for many months without seeing any single debt fully eliminated, which can feel discouraging even while the strategy is working correctly behind the scenes. This method suits people who are motivated by numbers and long-term math more than by frequent visible milestones.
Strategy 2: The Debt Snowball Method — Slightly Costlier, Behaviorally Stronger
Ordering debts from smallest to largest balance (regardless of interest rate) and attacking the smallest first means you eliminate individual debts faster and more frequently, even though this approach typically costs slightly more in total interest compared to the Avalanche method.
Why this trade-off is often worth it: behavioral finance research on debt payoff consistently shows that people who use the Snowball method are statistically more likely to complete their full debt payoff plan, precisely because the frequent visible wins (completely eliminating a debt every few months) sustain motivation through what is often a multi-year process.
Practical guidance for choosing between the two: if you’ve previously started and abandoned a debt payoff attempt due to lost motivation, Snowball is likely the better fit despite costing slightly more overall. If you’re confident in your ability to stay disciplined without frequent visible milestones, Avalanche saves genuine money.
Strategy 3: Increasing Income — Why This Multiplies the Other Strategies
Extra income directed entirely at debt doesn’t just add to your payoff amount — it compounds the effect of whichever method (Avalanche or Snowball) you’re using, since every additional dollar accelerates whichever debt you’re currently targeting. A person earning an extra $200 monthly through freelance work or selling unused items isn’t just paying off debt $200 faster per month — they’re shortening the entire remaining timeline non-linearly, since less total interest accrues on a shrinking balance throughout the accelerated payoff period.
Practical prioritization: among the income-increasing options, selling unused items provides the fastest initial cash injection with zero ongoing time commitment, making it a reasonable first step even while pursuing longer-term income increases.
Strategy 4: Cutting Expenses — The Specific Reasoning Behind “Temporary”
The word “temporarily” in this strategy matters more than it might first appear. Permanent, aggressive lifestyle cuts tend to trigger the same abandonment problem discussed in budgeting contexts — an unsustainably restrictive approach usually collapses within months. Framing these cuts explicitly as temporary, tied to a specific debt-free target date, makes the sacrifice psychologically easier to sustain.
The compounding math worth highlighting: cutting $300 monthly doesn’t just add $3,600 annually toward debt — when applied consistently to your highest-priority debt, it also reduces the total interest that would otherwise have accrued during the additional months, meaning the real impact is somewhat larger than the raw $3,600 figure alone suggests.
Strategy 5: Debt Consolidation — When It Helps, and When It Creates New Risk
Consolidating multiple high-interest debts into a single lower-interest loan can genuinely reduce total interest paid and simplify tracking multiple payments into one. However, this strategy carries a specific risk rarely emphasized enough: consolidation addresses the interest rate and payment structure, but does nothing on its own to address the spending behavior that created multiple debts in the first place.
Practical safeguard: if pursuing consolidation, consider closing or freezing newly-emptied credit accounts until the consolidation loan itself is fully repaid, specifically to remove the temptation of re-accumulating debt during the payoff period.
How Long Will It Actually Take? The Numbers That Make the Case for Extra Payments
Using a representative example of $10,000 in credit card debt at 20% annual interest:
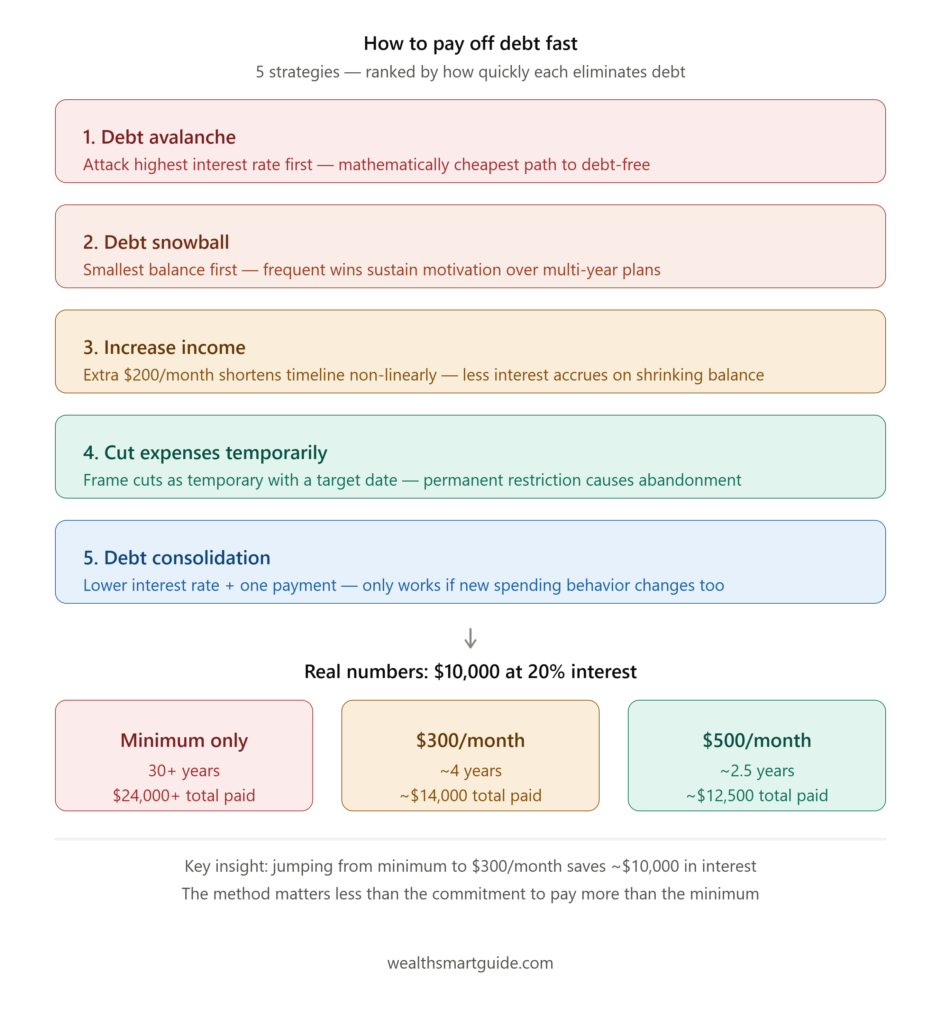
- Paying only the minimum: stretches to over 30 years, with total payments exceeding $24,000 — more than double the original debt paid in interest alone
- Paying $300 monthly: roughly 4 years, approximately $14,000 total paid
- Paying $500 monthly: roughly 2.5 years, approximately $12,500 total paid
The insight worth emphasizing: the jump from minimum payments to even a modest fixed monthly amount ($300) doesn’t just speed things up modestly — it fundamentally changes the total cost by roughly $10,000 in saved interest.
Mistakes to Avoid — The Reasoning Behind Each
Taking on new debt while paying off old debt: directly undermines progress under either method, since new interest-accruing balances compete with your existing payoff plan.
Not having a small emergency fund as backup: without at least a modest buffer ($500–1,000), an unexpected expense often gets placed directly on a credit card, effectively restarting the cycle.
Closing credit cards immediately after payoff: this can negatively affect your credit utilization ratio and average account age — keeping a paid-off card open with zero balance typically serves your credit profile better.
Giving up after one difficult month: a single month where an emergency forces a smaller-than-planned payment doesn’t invalidate months of prior progress.
Not celebrating small wins: for Snowball method users especially, acknowledging each fully eliminated debt reinforces the motivation that makes this method statistically more likely to be completed.
Once you’ve eliminated high-interest debt, the next logical step is redirecting those same monthly payments toward building wealth. For a practical starting point, see How to Start Investing with $100: A Beginner’s Guide — the same discipline that paid off debt applies directly to consistent investing. And if you’re looking to build the financial habits that prevent debt from recurring, 10 Money Habits That Will Make You Rich by 40 covers the behavioral foundation in detail.
Frequently Asked Questions
Should I pay off debt or invest first? Knowing how to pay off debt fast is especially important when interest rates exceed 7-8% For high-interest debt (above 7–8%), paying it off first is almost always the better mathematical choice, since the guaranteed “return” from eliminated interest typically exceeds uncertain market returns. For low-interest debt (student loans under 5%), the case for investing simultaneously becomes stronger.
How much of a difference does an emergency fund actually make during debt payoff? A significant difference. Without even a small emergency buffer, a single unexpected expense — a car repair, a medical bill — typically lands on a credit card, adding new interest-accruing debt just as you’re trying to eliminate existing debt. Even $500–1,000 set aside specifically for this purpose breaks that cycle.
Is debt consolidation always a good idea? Not automatically. Consolidation only helps if the new interest rate is meaningfully lower than your current rates, and if you have a credible plan to avoid accumulating new balances on the now-empty accounts. Without addressing the spending behavior that created the debt, consolidation can leave you worse off.
What’s the single most important decision in a debt payoff plan? Choosing between Avalanche and Snowball based on your actual behavioral tendencies — not which one looks better on paper. The mathematically optimal strategy you abandon halfway through costs far more than the slightly less optimal one you actually complete.
Conclusion: how to pay off debt fast the right way
The most effective strategies to pay off debt fast share one trait: they match the method to the person, not just the math. Paying off debt fast isn’t just about picking a method — it’s about matching the method to your actual behavioral tendencies (Avalanche for pure math efficiency, Snowball for sustained motivation), then compounding that method’s effect through increased income and temporary expense cuts. The numbers make clear that even modest additional monthly payments beyond the minimum dramatically shorten both the payoff timeline and total interest paid, making minimum-only payments one of the costliest passive financial decisions most people make without realizing the true long-term cost. Use this guide as your starting point for how to pay off debt fast in a way that actually sticks.